Mortgage Rates Jumped Back Above 7% — Here’s How Wake County Buyers Can Still Negotiate
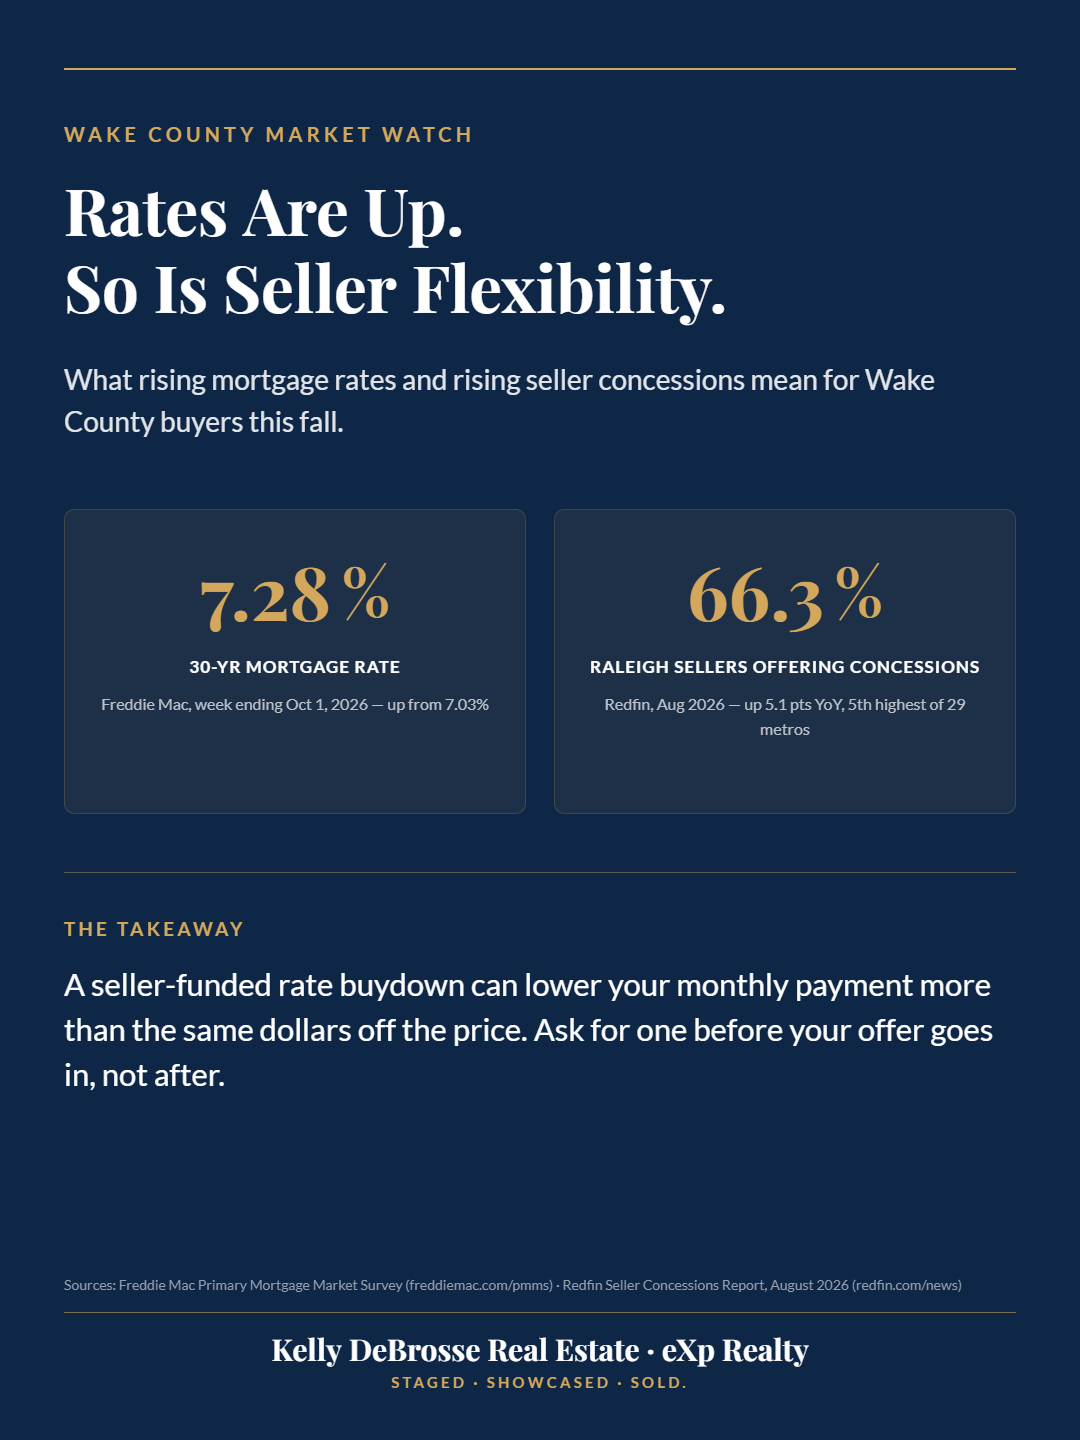
If you’ve been watching mortgage rates with a knot in your stomach the past few weeks, you’re not imagining it. The average 30-year fixed rate climbed to 7.28% for the week ending October 1, 2026, according to Freddie Mac’s Primary Mortgage Market Survey — up from 7.03% the week before, and a full percentage point higher than the 6.34% buyers saw this time last year.
That’s a real jump, landing at an odd moment: rates are rising even as the Triangle has quietly become one of the more buyer-friendly markets in the country. Together, those two trends change how a Wake County purchase should be negotiated right now.
Start with what’s happening on the seller side. In Redfin’s most recent concessions report, published September 18 and covering the three months ending August 31, 2026, 66.3% of Raleigh-area home sellers gave buyers some form of concession — money toward closing costs, repairs, or a mortgage-rate buydown — up 5.1 percentage points from a year earlier. That ranked Raleigh fifth among the 29 major U.S. metros Redfin tracks, behind only Atlanta, Charlotte, Phoenix and Las Vegas. Nationally, 44.7% of sellers gave concessions in August, up from 42.6% a year earlier and the highest August share since at least 2020 — with nearby Charlotte at 67.9%, a 9.3-point jump from last year and one of the largest increases of any metro in the country.
Put plainly: with rates back above 7%, more Wake County sellers than at almost any point in recent years are willing to help absorb that cost rather than lose a buyer altogether.
What this means if you’re buying in Raleigh, North Raleigh, or elsewhere in Wake County this fall: a seller concession isn’t a consolation prize — it’s often a more powerful tool than a straight price cut. A seller-funded rate buydown can lower your monthly payment by more than an equivalent dollar amount knocked off the purchase price would, because it’s attacking the actual cost driver (the rate) instead of the sale price. Asking for one, structured correctly with your lender, can matter more right now than haggling over the last few thousand dollars of list price.
A few practical notes before you write an offer. Concessions are typically negotiated as part of the offer itself, or during the post-inspection period — not added as an afterthought once you’re already under contract — so talk with your agent and lender about what to ask for before the offer goes in. Loan programs don’t all treat buydowns the same way, so get the real monthly-payment impact in writing before choosing between cash toward closing costs, a rate buydown, or a mix of both. And keep this in perspective: it’s market-wide context, not a guarantee for any specific house — a well-priced, well-maintained listing in a tight pocket of Wake County can still draw a clean offer with no concessions at all.
If you’re weighing whether to buy now or wait for rates to settle, the honest answer is that no one can time the rate market with precision. But the amount of help sellers are currently willing to offer is unusually high for this market, and that’s worth weighing alongside the rate itself before you decide to sit on the sidelines.
Sources: Freddie Mac Primary Mortgage Market Survey, freddiemac.com/pmms (week ending October 1, 2026); Redfin, “Nearly Half of Homebuyers Get Concessions From Sellers as Most Markets Tip in Buyers’ Favor,” redfin.com/news/home-seller-concessions-august-2026/ (published September 18, 2026).
Thinking about your own situation?
Call or text, or send me an email. We can start with a conversation.