Why Your Homeowners Insurance Premium Went Up (and What Wake County Homeowners Can Do About It)
If your homeowners insurance renewal notice looked bigger this year, you're not imagining it, and you're not alone. Wake County homeowners are in the middle of a two-year, state-approved base rate increase, and understanding where it comes from can help you handle it better at your next renewal.
What's actually happening
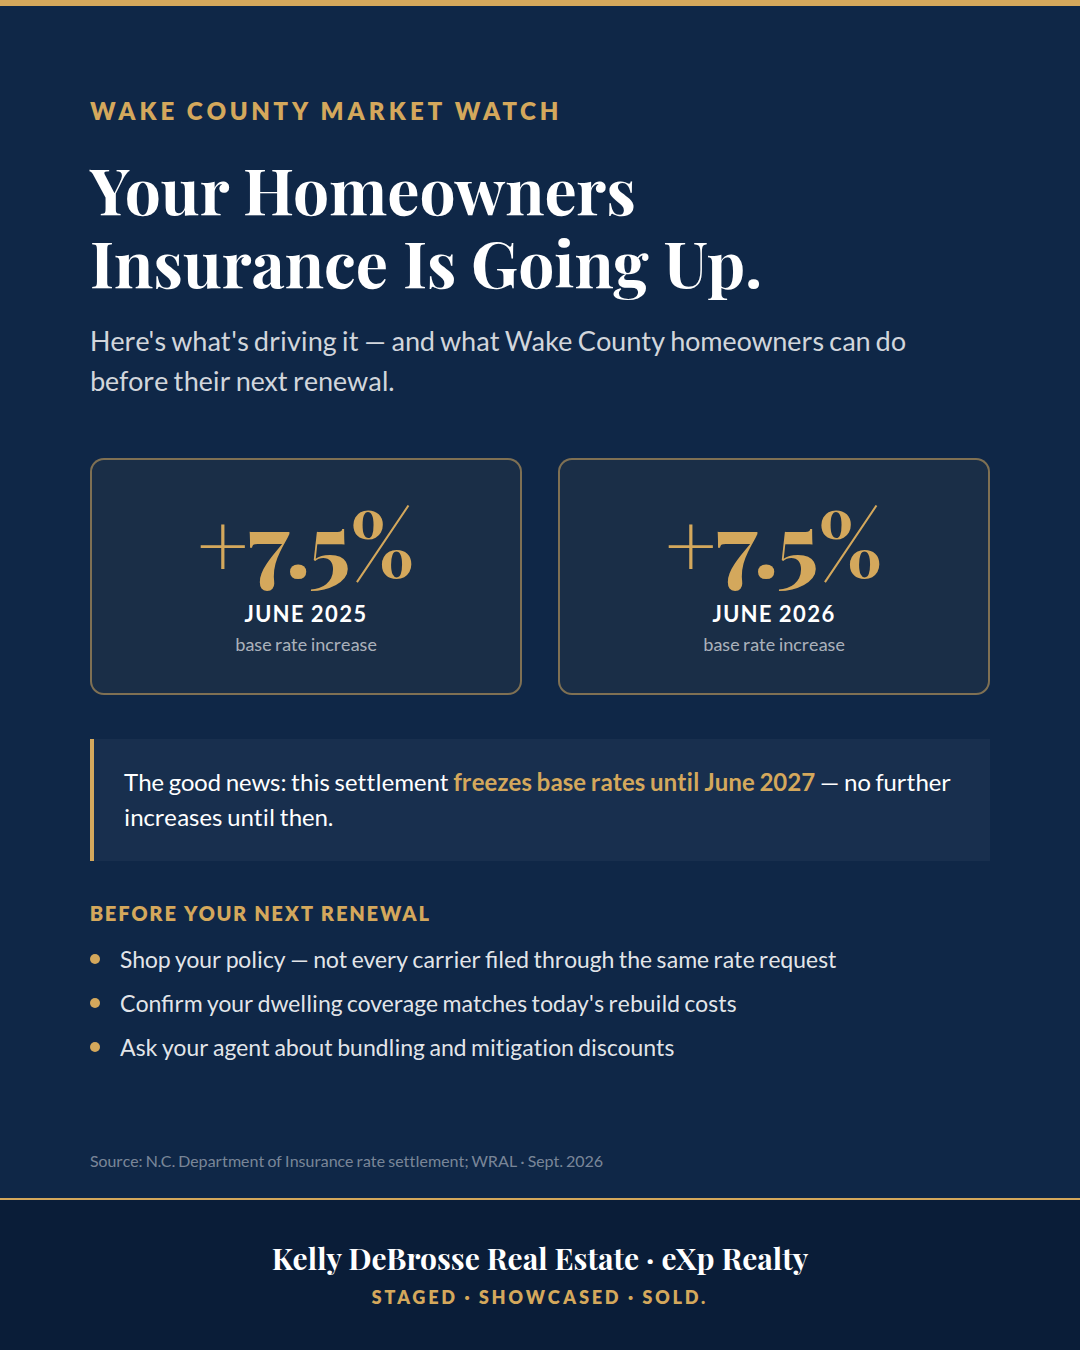
In 2023, the North Carolina Rate Bureau, the industry group that files rate requests on behalf of insurers, asked state regulators for a statewide average increase of 42.2%, with some territories facing proposed hikes as high as 99.4%. For the territory that covers Wake and Durham counties, the Rate Bureau asked for 39.8%. North Carolina Insurance Commissioner Mike Causey negotiated those numbers down substantially, settling on an average 7.5% base rate increase effective June 1, 2025, followed by another 7.5% increase on June 1, 2026, with no territory allowed to rise more than 35%. Commissioner Causey estimated the settlement saves North Carolina homeowners roughly $777 million compared to what insurers originally requested.
Wake and Durham counties landed right at that statewide average, 7.5% in both years. Other parts of the state saw very different outcomes. The barrier-island territory along the coast, covering Brunswick, Carteret, New Hanover, Onslow and Pender, went up 16% in 2025 and another 15.9% in 2026. Neighboring Orange County, by contrast, saw only 3.4% and then 3.2%. The insurance industry has pointed to inflation in building material and labor costs, along with major storm losses, as the main drivers.
The good part: a rate freeze
The settlement includes a real benefit for homeowners. No further base rate increases are allowed before June 1, 2027. So if you've already absorbed both rounds of this increase, your base rate shouldn't move again for a while, barring a new filing down the road.
What to do at your next renewal
A few practical steps, echoing guidance from the NC Department of Insurance:
Shop your policy. Not every insurer priced their policies through this same rate filing, so premiums for comparable coverage can vary meaningfully between carriers.
Double-check your dwelling coverage amount. With building material costs cited as a factor in these increases, it's worth confirming your coverage limit still reflects what it would actually cost to rebuild your home today, not just its market value.
Ask about discounts. Bundling home and auto, security systems, newer roofs, and other mitigation features can sometimes offset part of the increase.
Consider your deductible. Raising it can lower your premium, but make sure the trade-off still fits your comfort level for out-of-pocket costs after a claim.
One more note for landlords and investors
Separately, dwelling fire policies, typically used for rental and investment properties, have their own rate case. The NC Rate Bureau originally sought a combined 68.3% increase over two years, but Commissioner Causey negotiated that down to 5% per year, effective October 1, 2026 and October 1, 2027. That first increase lands within days, so if you own rental property in Wake County, it's worth budgeting for now.
Whether you're staying put, buying, or selling in Wake County this year, insurance is one more line item worth factoring into your numbers early, before it shows up as a surprise at closing or renewal.
Thinking about your own situation?
Call or text, or send me an email. We can start with a conversation.